
Cost of Living in Ada, MI: Housing, Taxes and Everyday Expenses
Is Ada, Michigan expensive to live in?
Ada can be an expensive place to buy a home, particularly if you are looking for a newer house, a large lot, or a location close to Ada Village. But a household’s true cost of living is about more than the purchase price. Taxes, utilities, insurance, commuting, maintenance, childcare, and the way you spend your time all influence the monthly total.
Our advice is to start with the particular home and lifestyle you are considering, not a generic calculator that gives one “Ada cost-of-living score.” The size of the home, the school district and other taxing jurisdictions, whether there is an HOA, and even the length of the driveway can make two Ada households’ budgets look very different.
Ada Township at a glance: U.S. Census Bureau, 2020–2024 American Community Survey estimates
| Measure | Ada Township estimate |
| Median value of owner-occupied homes | $544,700 |
| Median selected monthly owner costs, with a mortgage | $2,458 |
| Median selected monthly owner costs, without a mortgage | $840 |
| Median gross rent | $2,139 |
| Median household income (in 2024 dollars) | $168,468 |
| Mean travel time to work (workers age 16 and older) | 19.7 minutes |
Source: U.S. Census Bureau QuickFacts, Ada Township (2020–2024 American Community Survey). “Selected monthly owner costs” is a broad Census housing-expense measure, not a mortgage-payment quote. It includes mortgage payments, real estate taxes, qualifying insurance, utilities and fuels, and applicable condominium fees. It does not cover every repair, maintenance expense, or other household cost. Avoid adding taxes and utilities to that Census figure a second time.
These figures describe Ada Township households during the Census survey period. They are not current listing prices, loan quotes, rents for units currently available, or a recommended budget for your household. The broader Ada mailing-address area can include homes in other townships, so the numbers are best used for background context rather than as a price tag for every property with “Ada” in its address.
Housing is usually the biggest cost decision in Ada
Buying a home: what the numbers really mean
When someone asks us about the cost of living in Ada, housing is usually where the discussion begins. The community has a mix of established subdivisions, custom properties, wooded or rural-feeling homes, village-area attached housing, and new construction. That variety is attractive, but it also means an Ada-wide average may describe very few of the homes a buyer is actually considering.
The Census Bureau’s $544,700 median owner-occupied home value is a historical survey estimate for Ada Township. It is not the same as the median sale price of homes that closed last month or the asking price of homes currently on the market. Those measures answer different questions. A neighborhood with few recent transactions can also produce a misleading short-term median, particularly if one period happens to include several high-end homes.
Instead, compare recent sales of similar homes in the part of Ada where you want to live. A newer home near the village should not automatically be compared with an older property on acreage simply because both have the same mailing city. Look at square footage, lot size, age, condition, location, amenities, and the cost of upgrades or repairs. You can start by browsing Ada homes for sale and then narrow the search to realistic alternatives.
What your housing budget actually buys
Your budget can lead to very different housing experiences. An attached home or a smaller village-area property may trade private yard space for convenient access to shops and trails. An established subdivision can offer a mature neighborhood, while a larger-lot home may give you more separation between neighbors but add maintenance. A new build can offer a modern layout, although the total price after options, upgrades, and finishing work may be higher than the initial builder quote.
The most useful question is not simply “How much is an Ada house?” It is “What will this specific house cost me to own and operate?” That includes the payment, taxes after purchase, insurance, possible HOA dues, utilities, and the work that the property will need. For buyers considering newer homes, our guide to Ada new construction neighborhoods explains how community setting and lot size affect the comparison.
Renting in Ada
Renting may be appealing if you are moving to West Michigan and want to learn the area before committing to a purchase. It can also be difficult to compare with buying because the rental mix is not the same as the homes typically listed for sale. Larger single-family rentals, smaller units, and attached homes are different products, and available choices can be limited at any given time.
The Census Bureau reported a median gross rent of $2,139 for Ada Township in its 2020–2024 estimates. Gross rent includes contract rent plus applicable renter-paid utilities and heating fuels. It should not be presented as a live asking rent for a currently available apartment or house. Before using a rental price in your budget, verify whether utilities, lawn service, snow removal, pet charges, and parking are included.
Property taxes in Ada: the expense buyers should not overlook
Property taxes deserve their own conversation in Michigan because the amount listed for the current owner may not be what a buyer pays after purchasing the home. Michigan generally caps annual growth in taxable value while an owner holds property, subject to legal rules, but a qualifying transfer typically results in taxable value becoming uncapped in the calendar year following the transfer. That means an established house can have a tax history that does not reflect a new buyer’s projected bill.
Michigan generally assesses property at 50% of its true cash value. State equalized value (SEV) is the assessed value after applicable equalization adjustments. Taxable value, which is used to calculate property taxes, may be lower than SEV for a longtime owner. After a nonexempt transfer of ownership, taxable value generally resets to the property’s SEV in the following calendar year. This does not mean an assessor automatically sets the value at half of the home’s sale price; the assessment is based on the property’s true cash value under Michigan rules. Millage is the tax rate, with one mill equal to $1 per $1,000 of taxable value. The combined millage depends on the property’s taxing jurisdictions and school district.
Owner-occupants should also ask about Michigan’s principal residence exemption (PRE). Eligible principal residences can be exempt from up to 18 mills of local school operating tax. That does not eliminate all property taxes, and eligibility should never be assumed without reviewing the rules and the property’s actual status.
For budgeting, we recommend three steps. First, identify the parcel, township, and school district. Second, ask for a realistic estimated taxable value and millages after a transfer and, for a new build, after the improvements are assessed. Third, verify whether you would qualify for the PRE or any other applicable relief. The Michigan Department of Treasury’s property-tax resources and local assessing office are good places to start. Do not simply divide a home’s listed annual taxes by 12 and treat that as your permanent monthly obligation.
Why new construction taxes can be especially confusing
A vacant lot might carry a relatively small tax bill because a completed house has not yet been assessed. Once the completed home’s value is reflected in the assessment, its taxable value can change substantially. Buyers should discuss timing and likely tax treatment with the builder, assessor, and lender before relying on a projected escrow payment. The same caution applies when the home is completed shortly before sale or when a seller’s tax history reflects years of capped taxable-value increases.
Do different Ada addresses have different taxes?
Yes. An Ada mailing address does not necessarily mean a property is in Ada Township. Confirm the municipality, school district, and other applicable taxing jurisdictions for each parcel. Two houses with similar market prices may therefore have different tax bills. An online average “Ada tax rate” cannot capture all of that variation, so compare specific parcels instead.
Utilities and regular household expenses
A well-built, efficiently sized home may cost less to heat and maintain than a larger, older house, but square footage is only part of the story. Insulation, windows, heating equipment, fuel type, occupant habits, and whether you have water and sewer service or private systems all matter. Ada-area properties vary enough that a single monthly utility figure could be more misleading than helpful.
| Expense | What changes the cost in Ada | How to estimate it |
| Electricity and heating | Home size, insulation, fuel type, equipment, thermostat settings | Request a year of actual bills and ask about seasonal peaks |
| Water and sewer | Public service versus well/septic, usage, meter and service charges | Confirm the parcel’s utility setup and current posted rate schedule |
| Internet and mobile | Provider availability and service level at the address | Check serviceability using the exact street address |
| Groceries and dining | Household size, shopping patterns, frequency of meals out | Use current household spending and adjust for your habits |
| Transportation | Cars, commute frequency, fuel, maintenance, insurance | Calculate real routes and costs for all vehicles |
| Home upkeep | Lot size, age, exterior materials, snow and lawn work | Obtain quotes and set aside a maintenance reserve |
| HOA or condo dues | Community services, reserves, coverage and rules | Read current association documents and budgets |
| Childcare and activities | Provider, schedule, ages, and extracurricular choices | Request current local quotes rather than regional averages |
Electricity, heating, water, and sewer
Michigan winters make heating an important budget line. A home’s age and efficiency features can influence the amount spent, but it is worth asking for real bills instead of assuming “newer” means “cheap to heat.” A home with expansive glass, high ceilings, or much more square footage can still use substantial energy. For any property, especially one in a more rural setting, confirm the heating fuel and equipment.
Some Ada-area homes have public water and sewer, while others rely on a private well and septic system. Public-utility customers should understand fixed service charges as well as usage charges. Owners of private systems have different costs, including inspections, pumping, treatment equipment, repairs, and eventual replacement. Ask for service records and relevant inspections rather than thinking of private systems as having no monthly cost.
Groceries, restaurants, and everyday shopping
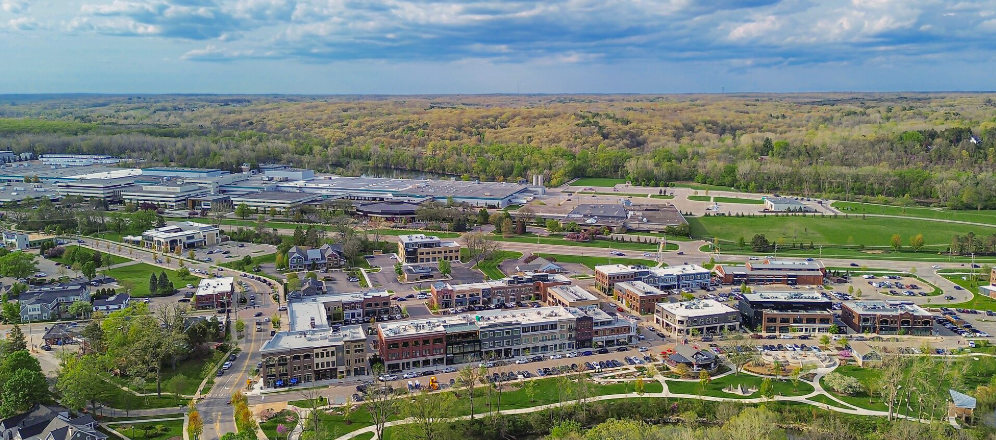
Ada Village gives residents convenient places to meet for coffee, go out to dinner, and browse local businesses. You will also find broader shopping options elsewhere on the east side of Grand Rapids. For most households, grocery spending will reflect how many people live at home, where they shop, and how frequently they eat out much more than a town-specific index.
If you are relocating, a useful exercise is to keep your present grocery and dining budget intact at first. Then check the stores and restaurants you would actually use from the prospective home. A household that cooks most meals and shops in bulk will have a different spending pattern from one that regularly visits restaurants and specialty markets, even if both live in the same subdivision.
Transportation and commuting
Ada has a walkable village core, but many neighborhoods are more spread out. Driving is a regular part of life for households outside the central village area. Transportation costs may include car payments, insurance, gas, tires, winter maintenance, and parking, along with the time spent traveling between destinations.
For context, the Census Bureau reports a mean commute of 19.7 minutes for workers living in Ada Township in the 2020–2024 survey period. That is an overall historical measure, not an expected commute from any particular house. A home close to your job may reduce your weekly driving, while a property with a more secluded setting may lengthen regular trips. Test your own route at the hours you are likely to travel.
Maintenance, landscaping, and winter expenses
This is where a home with a beautiful, sprawling lot can surprise a buyer. A larger lawn can mean more mowing, fertilizing, landscaping, and watering. Mature trees can add character and shade but may also require trimming or cleanup. Long driveways and private drives need attention when snow arrives. Even new construction often requires spending on landscaping, window treatments, patios, storage, or other finishing work after moving in.
A good budget includes an annual reserve for repairs and replacements rather than assuming that every month without a major expense means ownership is inexpensive. For attached housing, find out which exterior and maintenance costs are paid through association dues and which remain your direct responsibility. “Low maintenance” is only useful when you know precisely what is included.
Childcare, healthcare, and recreation
For households with children, childcare and after-school activities may be among the biggest costs after housing. Healthcare spending depends heavily on insurance, providers, and the needs of the individuals in the household. Recreation costs can be modest if you enjoy local parks and trails, or much higher if your routine includes lessons, memberships, or frequent outings.
Rather than relying on a single Ada-wide average, build your estimate from your actual needs. Contact providers, compare current prices, and consider whether a particular home’s location increases or decreases the number of trips your household makes each week.
Build a realistic monthly budget for living in Ada
A household considering a move should model both the first year of ownership and a typical year after settling in. One-time relocation expenses, closing costs, furniture, blinds, landscaping, and renovation work can make the first year unusually expensive. Those should not get lost inside an overly simple monthly mortgage calculation.
Use the following worksheet with actual numbers for the home you are considering. The goal is not to predict a universal “cost to live comfortably in Ada.” It is to see what you personally would be committing to, with room for savings and unexpected expenses.
Avoid double-counting: Enter mortgage principal and interest separately from taxes and insurance. If you start with a lender’s total monthly payment, check which expenses are already included in escrow. For rentals, do not list utilities separately if they are included in rent. This worksheet estimates your personal future expenses and is separate from the Census “selected monthly owner costs” measure.
| Monthly budget line | Your estimate |
| Mortgage principal and interest or rent | $________ |
| Property taxes based on a post-transfer estimate | $________ |
| Homeowners or renters insurance | $________ |
| Mortgage insurance, if applicable | $________ |
| HOA or condo fee, if applicable | $________ |
| Electricity and heating | $________ |
| Water/sewer or reserve for private systems | $________ |
| Internet and mobile service | $________ |
| Groceries and household supplies | $________ |
| Transportation and vehicle expenses | $________ |
| Childcare and after-school care | $________ |
| Health insurance and out-of-pocket healthcare | $________ |
| Recreation, memberships, and activities | $________ |
| Home maintenance, lawn care, and snow removal reserve | $________ |
| Savings contributions | $________ |
| Other debt payments | $________ |
| Other discretionary spending | $________ |
| Estimated monthly total for the expenses listed above | $________ |
When you compare two Ada houses, complete the worksheet for both. A less expensive home with higher taxes, a long commute, and significant deferred maintenance may not offer the monthly savings you expected. Conversely, a more expensive property in a location that makes everyday life easier may better fit your budget and priorities. Your lender can help with payment scenarios; your Realtor can help identify the property-specific questions; and the township or assessor can help clarify tax details.
Ada vs. Grand Rapids, Cascade, and East Grand Rapids: What changes?
Homebuyers relocating to the east side often compare Ada with Grand Rapids, Cascade, and East Grand Rapids. They are close enough to be part of the same broad housing search, but the way you live and spend money can differ considerably. We prefer to compare housing and property-level expenses rather than claim that one community is a fixed percentage more expensive than another.
| Community | Housing considerations | Cost tradeoffs to investigate |
| Ada Township | Village-area options, established neighborhoods, larger lots, custom homes | Purchase budget, post-transfer taxes, yard upkeep, car travel beyond the village |
| Grand Rapids | Wide range of city neighborhoods, house ages, and lot sizes | Property-specific tax jurisdiction, parking, home condition, commute |
| Cascade Township | Established suburbs and larger-lot areas, including some Ada-address homes | Tax and school boundaries, housing type, utilities, maintenance |
| East Grand Rapids | Close-in established homes, compact neighborhood pattern, Reeds Lake area | Location premium, property taxes, updates and repairs on older homes |
Ada and East Grand Rapids are a particularly common comparison. East Grand Rapids is known for compact neighborhoods near Gaslight Village and Reeds Lake, while many Ada buyers are seeking more land, modern construction, or a wooded setting. The costs still depend on the exact homes being compared. Read our full guide to Ada vs. East Grand Rapids for the lifestyle and housing differences.
Do not overlook neighboring communities when comparing homes marketed with Ada mailing addresses. Municipal boundaries do not always match how people informally describe the area, and jurisdiction matters more to taxes and services than the mailing city. When choosing between communities, identify a few comparable houses and then check taxes, insurance, service arrangements, HOA obligations, travel time, and upcoming work on each property.
Is living in Ada worth the cost?
That depends on what you value and what the purchase requires you to give up. Buyers often consider Ada because they like the village, river landscapes, wooded neighborhoods, access to parks and trails, and the possibility of more space or newer construction. The same characteristics can introduce a larger purchase budget, more driving, or higher ongoing property maintenance. There is no universal answer for every household.
We find it helpful to separate the lifestyle decision from the financial decision. First, decide whether you actually want the type of setting the home offers. Next, put the real costs into a monthly and annual budget, including expenses that are not obvious in the listing. If both the lifestyle and the numbers work, Ada may be a strong fit. If not, nearby east-side communities may offer a better compromise.
For a broader look at the benefits and possible downsides beyond the household budget, explore the pros and cons of living in Ada.
Learn more: Pros & Cons of Living in Ada
Frequently asked questions about the cost of living in Ada
Is Ada, MI more expensive than Grand Rapids?
Ada often attracts buyers shopping for larger properties and higher-priced homes, so housing can be the biggest difference. But costs vary by neighborhood, home size, condition, and tax jurisdiction. Compare actual candidate homes and their full monthly expenses rather than relying on one blanket comparison.
What is the average home price in Ada?
There are several different measures. The Census Bureau’s 2020–2024 estimate of median owner-occupied home value for Ada Township was $544,700. That is not a current average sale price or listing price. For today’s market, use a dated local MLS analysis of comparable recent sales in the specific area you are considering.
How much are property taxes on an Ada home?
There is no single accurate figure for every Ada-address property. Your bill depends on taxable value, applicable millages, exemptions, and the property’s jurisdictions. In Michigan, a qualifying ownership transfer generally uncaps taxable value the following calendar year. Request a post-purchase estimate instead of relying only on the seller’s existing bill.
Is renting in Ada cheaper than buying?
Renting can require less cash up front and may shift certain maintenance responsibilities to a landlord. Buying can build equity as you pay down mortgage principal, although changes in property value affect how much equity you have. Ownership also brings taxes, insurance, repairs, and potentially association fees. The better financial choice depends on the actual rental and purchase options, the intended length of stay, and your budget.
Are utilities expensive in Ada?
There is no one-size-fits-all utility bill. Heating fuel, home size, insulation, household usage, and public water/sewer versus private systems all matter. Ask for utility histories and confirm service arrangements at the specific property.
What income do you need to live comfortably in Ada?
There is no universal salary threshold. Ada Township’s 2020–2024 median household income was $168,468, but that is a description of surveyed households, not the amount a newcomer must earn. The useful calculation is your own after-tax income minus housing, transportation, essential expenses, savings, and the margin you want to preserve.
Do Ada neighborhoods have HOA fees?
Some developments and attached-home communities have homeowners associations, while other homes do not. Fees and what they cover vary widely. Read current documents, ask about reserves and assessments, and include any association costs in the budget.
Make an Ada home budget with May Group Realtors
Ada can offer a terrific combination of village life, outdoor access, and distinctive homes, but the right home is the one that works financially as well as personally. Before getting attached to a listing, compare the likely post-transfer taxes, association obligations, utility setup, lot maintenance, and commuting costs along with the purchase price.
May Group Realtors can help you evaluate the differences between specific Ada homes and nearby east-side options. Explore homes for sale in Ada, learn more about living in Ada, Michigan, or connect with our team to discuss which neighborhood and property type makes sense for your goals.